Allowance: What the Research Says
What the research says about allowance
The TL;DR version is that an allowance helps a little, but how parents use and talk about allowance with their kids matters much more. There are ways to teach healthy mindsets by age by setting goals that match where kids are developmentally.
The best evidence found that young adults who got an allowance growing up reported modestly higher financial responsibility.
A 2026 recent study used PISA 2018 test results from about 38,000 15-year-olds in 19 countries, including the US, to compare three groups: teens who got an allowance as a gift, teens who earned one by doing tasks, and teens who got none. After matching kids on family income and math skill, freely gifted allowance was linked to slightly higher financial literacy scores (about 3 points on a test that averages around 500) and earned allowance to slightly lower scores, a relatively small difference.
The results about are modest. Allowances can work when applied consistently, but the adult conversations behind them have a greater effect on financial capability.
Allowance as kids grow: make it about goals
A helpful way to structure allowance is line up goals for children as they age. Starting from an emphasis on planning in pre-school age to a handoff of responsibility in the teen years.
Ages 3 to 5: Make the goal into a plan kids can see
The goal at this age is to practice holding a small plan in mind. In one study of preschoolers, being able to plan ahead predicted their ability to save better than self-control did.
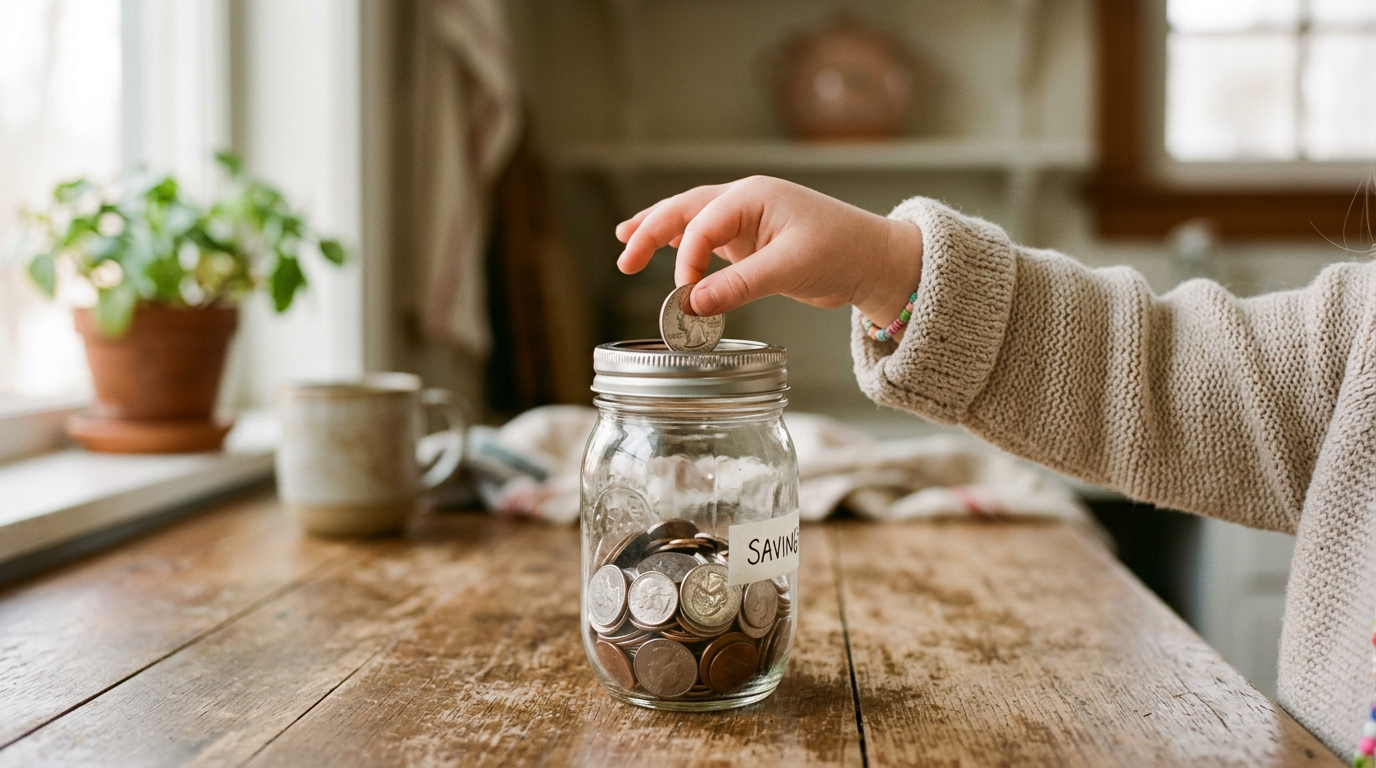
When offered the opportunity, most three-year-olds would take a reward immediately but begin to wait when they turn four. Seeing coins pile up in a clear jar can help kids visualize saving. To help practice healthy mindsets, we should keep everything concrete: "This coin is for now, this one goes in the jar, and on Saturday we count the jar together."
Ages 6 to 9: Make the goal around noticing trade offs
At this age, the goal is understanding that money spent now is money that is no longer there, and noticing how that feels. Kids this age can already say whether spending feels easy or if there is emotional friction.
A save-up goal of two or three weeks is long enough to feel the wait and short enough to finish. When a kid makes a spending decision we would not have made, indicate it once and hand the decision back to them: "I'd save for the bike, but it's your money."
Ages 10 to 13: Make the goal around responsibility in one spending category
The goal shifts to managing one real piece of their own spending, like school snacks or gifts for friends. Tweens learn a lot by watching, and an allowance paired with financial ownership and mentorship from adults is linked to stronger money habits. This is also a good age to introduce digital money as real currency, since younger kids often have trouble connecting the concepts of physical money to electronic funds like tap-to-pay.
As the month starts, we tell kids: "This covers snacks until the 30th. If it runs out early, we'll talk about it, but I won't top it up."
Ages 14 to 18: the goal is a handoff with adult support for decision making
By high school the goal is handing over real decisions. An older 1990 study found an allowance on its own did little for teens, and what seemed to matter more is having real control over the money. At home, that can look like merging clothing and phone money into one monthly budget in an account that an adult can co-manage.
At this stage, we communicate to teens in plain and concise language what is changing and how we will support them: "Clothes are your budget now. I'm around if you want a second opinion."
Takeaways
Across every age, the research points the same way: the amount of the allowance matters less than what comes with it. What helps is a goal that fits where a kid is developmentally, and a grown-up who keeps talking about money while handing over a few more decisions each year. An allowance is practice with money while the stakes are still small, and adults can be there to help kids build their healthy values and mindsets around money.
References
Chen, L., & Yeung, W.-J. J. (2023). Delayed gratification predicts behavioral and academic outcomes: Examining the validity of the delay-of-gratification choice paradigm in Singaporean young children [Preprint]. PsyArXiv. https://doi.org/10.31234/osf.io/nr5x9
Chowdhury, A. (2021). Financial socialization for digital natives: A new way to teach children about money [Master's thesis, Ryerson University]. https://doi.org/10.32920/ryerson.14651556
Collins, J. M., & Odders-White, E. R. (2021). Allowances: Incidence in the US and relationship to financial capability in young adulthood. Journal of Family and Economic Issues, 42(3), 533–544. https://doi.org/10.1007/s10834-020-09748-y
Drever, A. I., Odders-White, E., Kalish, C. W., Else-Quest, N. M., Hoagland, E. M., & Nelms, E. N. (2015). Foundations of financial well-being: Insights into the role of executive function, financial socialization, and experience-based learning in childhood and youth. Journal of Consumer Affairs, 49(1), 13–38. https://doi.org/10.1111/joca.12068
Grusec, J. E., Goodnow, J. J., & Cohen, L. (1996). Household work and the development of concern for others. Developmental Psychology, 32(6), 999–1007. https://doi.org/10.1037/0012-1649.32.6.999
Kamawar, D., Connolly, K., & Astle-Rahim, A. (2019). Preschoolers' saving behavior: The role of planning and self-control. Child Development, 90(4), e407–e420. https://doi.org/10.1111/cdev.13037
Kim, J., & Chatterjee, S. (2013). Childhood financial socialization and young adults' financial management. Journal of Financial Counseling and Planning, 24(1), 61–79.
Miller, J., & Yung, S. (1990). The role of allowances in adolescent socialization. Youth & Society, 22(2), 137–159. https://doi.org/10.1177/0044118X90022002002
Perry, M., Chen, Z., & Castro, A. (2026). It's a life lesson: The role of unconditional cash in financial socialization of youth. Journal of Applied Youth Studies. Advance online publication. https://doi.org/10.1007/s43151-026-00214-4
Smith, C. E., Echelbarger, M., & Gelman, S. A. (2018). Spendthrifts and tightwads in childhood: Feelings about spending predict children's financial decision making. Journal of Behavioral Decision Making, 31(3), 446–460. https://doi.org/10.1002/bdm.2071
Strapazzon, I. C., França, M. T. A., & Frio, G. S. (2026). "Papai ou mamãe pode me dar uma mesada?" Uma análise sobre alfabetização financeira no PISA 2018 a partir do efeito da mesada ["Mom or dad, can I have an allowance?" An analysis of financial literacy in PISA 2018 through the allowance effect]. Estudos Econômicos, 56(1). https://doi.org/10.1590/1980-53575613img
Come Find Us
Follow us on Instagram [@sattakids\_](https://www.instagram.com/sattakids_/) to see how kids are practicing money choices at every age.
Satta helps children build money confidence through daily play — so the habits start early and the feelings around money start healthy. Download Satta in the App Store and start your child's money journey! [***Try Satta today***](https://apps.apple.com/us/app/satta-money-smart-kids/id6751374502)*.*